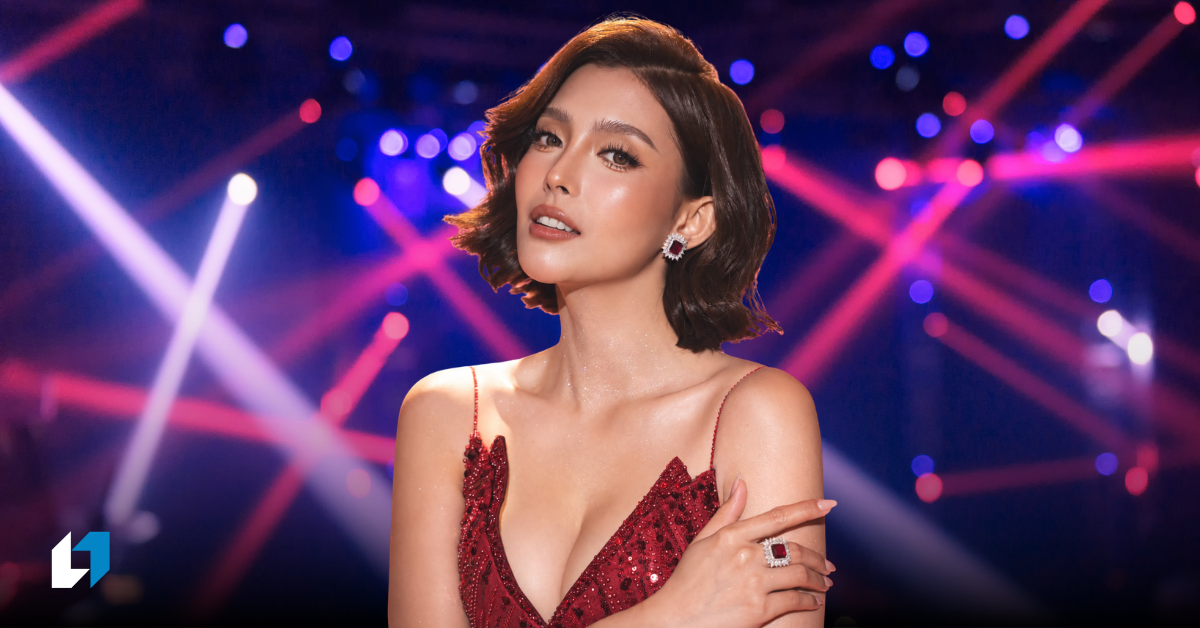
Before Analyn Barro became a familiar face on Philippine television, she was a college student in Bacolod who had not planned on entering show business.
Her opportunity came when she joined the sixth season of GMA’s reality talent competition StarStruck. It became her entry into the entertainment industry.
“StarStruck Batch Six po ako,” Barro recalls. “Doon po ako nakilala at doon po ako nagsimula.” analyn barro
Her career continued after the competition. One of her biggest opportunities came when she joined Bubble Gang, which she describes as an important training ground. On some days, she had to perform as many as 12 to 15 sketches.
“I guess my first big break was joining Bubble Gang,” she says. “Parang yun yung naging training ground ko, especially for acting.” analyn barro
But as Barro started to earn her own money, she also had to learn something that her work in television could not teach her: how to keep it.
When ₱50,000 felt like a lot of money
Barro remembers receiving around ₱50,000 from one of her early projects in 2016.
For someone at the start of her career, the amount seemed substantial. She did not yet have a system for deciding how much should be saved and how much she could spend.
“I think I did a little bit of shopping,” she recalls.
There were also frequent outings and expenses when she visited her family in Ormoc, Leyte. Looking back, Barro describes her financial behavior at the time simply as “more of spending and not saving.” analyn barro
Eventually, she checked her passbook. There was only about ₱2,000 left. “Puro gastos lang ako nang gastos,” she recalls. “Tapos yung natira na lang sa passbook ko, ₱2,000.”
That was when Barro realized how quickly money could disappear. “Doon ko na-realize na parang, ah, ang bilis pala maubos ng pera kapag gastos ka nang gastos,” she says.
The experience shows a common problem when someone begins to earn more money. A larger paycheck creates more room to spend, but without a plan for how much should remain untouched, spending can expand until there is little left.
The problem is therefore not always how much a person earns. It can also be how much of that income remains available to spend.
She stopped relying on willpower
Barro did not respond to her ₱2,000 balance by simply promising herself that she would become more disciplined.
Instead, she changed the system around her money. Her mother worked as a banker, so Barro asked her for help.
“Pwede ba tayong mag-joint account? Can you handle my money? And can you just give me a monthly allowance from my own money?” she recalls asking her mother.
Barro emphasizes that her mother did not ask her for financial support. The arrangement was meant to protect Barro’s earnings from her own tendency to spend them.
The strategy was simple, but its financial logic was powerful. Instead of keeping all her earnings readily available, Barro limited the amount she could use for everyday spending. Her mother effectively helped separate money intended for the future from money available today.
In behavioral finance, this resembles a commitment device, an arrangement that makes it harder for someone to abandon a financial goal when temptation arises.
Most people do not need to give control of their savings to a parent to achieve the same effect. Automatic bank transfers, separate savings accounts and payroll deductions can serve a similar purpose. Money gets set aside before it can become part of the spending budget.
Barro herself describes the lesson more simply. “Kailangan mo nang madapa bago mag-save,” she says.
Now 60 percent goes to savings
Barro’s system has become more disciplined since that experience. She says she still has a joint account with her mother, who gives her a monthly allowance that she can spend. When Barro earns additional income from other projects, she can place the money in another account.
“As I’ve told you, joint account kami ng mom ko ngayon,” she says. “So she gives me a monthly allowance na pwede ko lang gastusin.”
Her current savings target is unusually high. “Siguro 60% save,” she says. The remaining 40 percent can cover expenses and things she wants to enjoy, including travel.
“60% goes to the bank. Lagi,” she says. “I’m really strict with money.” A 60 percent savings rate is not necessarily a target everyone should copy. Someone who pays rent, supports children or parents, or carries other large fixed expenses may not have enough disposable income to save anywhere near that percentage.
What is more useful is the principle behind Barro’s rule. She decides how much she wants to keep before deciding how much she can spend.
Consider two people with different incomes. Someone who earns ₱100,000 a month but saves only 10 percent retains ₱10,000. Someone who earns ₱60,000 but saves 30 percent retains ₱18,000.
Higher income can improve someone’s finances, but only if at least part of the increase is retained. Otherwise, a bigger paycheck can simply finance a more expensive lifestyle.
“Hindi laging fiesta”
Barro’s approach becomes even more relevant because show business does not provide a predictable paycheck. There can be periods with several projects and other periods with fewer opportunities. Freelancers, entrepreneurs, salespeople and other workers with variable incomes face the same challenge.
“Hindi nga laging fiesta. Hindi laging malaki yung kinikita,” Barro says. This uncertainty affects what she does when a large paycheck arrives.
“Kapag may chance na malaki yung chunk na kinita, tabi agad,” she says. “Dapat i-deposit mo na yun para hindi mo na siya magastos.” This reverses the temptation that often accompanies an unusually good month.
If income suddenly doubles, it is easy to treat the increase as additional spending money. But if that higher income is temporary while the new expenses become permanent, the result can be financial stress once earnings return to normal.
For someone with irregular income, a strong month can instead provide a buffer for a weak one. The greater the uncertainty surrounding future earnings, the more valuable that financial cushion can become.
Saving is only part of the equation
Barro does not believe that financial discipline means refusing to enjoy money.
Her philosophy has expanded from simply trying not to spend everything she earns to finding a place for saving, spending and investing.
“I always try to find the balance of saving, spending, and investing,” she says. Each serves a different purpose. Savings can provide liquidity for emergencies or periods when income declines. Investments can help money grow over longer periods. Spending allows someone to enjoy the rewards of work today.
The challenge is deciding how much goes to each before lifestyle expenses absorb everything. Barro learned that lesson early. Her solution may seem unusually strict. She asked her mother to help control her money, accepted a monthly allowance from her own earnings and later adopted a 60 percent savings target.
But the broader principle does not require the same arrangement. Financial discipline can become easier when saving is built into the system rather than left to whatever happens to remain at the end of the month.
For Barro, it took seeing only ₱2,000 left in her bank account to understand the difference. She had already learned how to earn money. What she needed to learn was how not to spend all of it.