A new way of thinking about global conflict shows how events thousands of kilometers away can reach Filipino consumers, businesses and investors through oil, trade, technology and financial markets.
The Philippines may be geographically removed from many of the conflicts reshaping the world, but its economy is not.
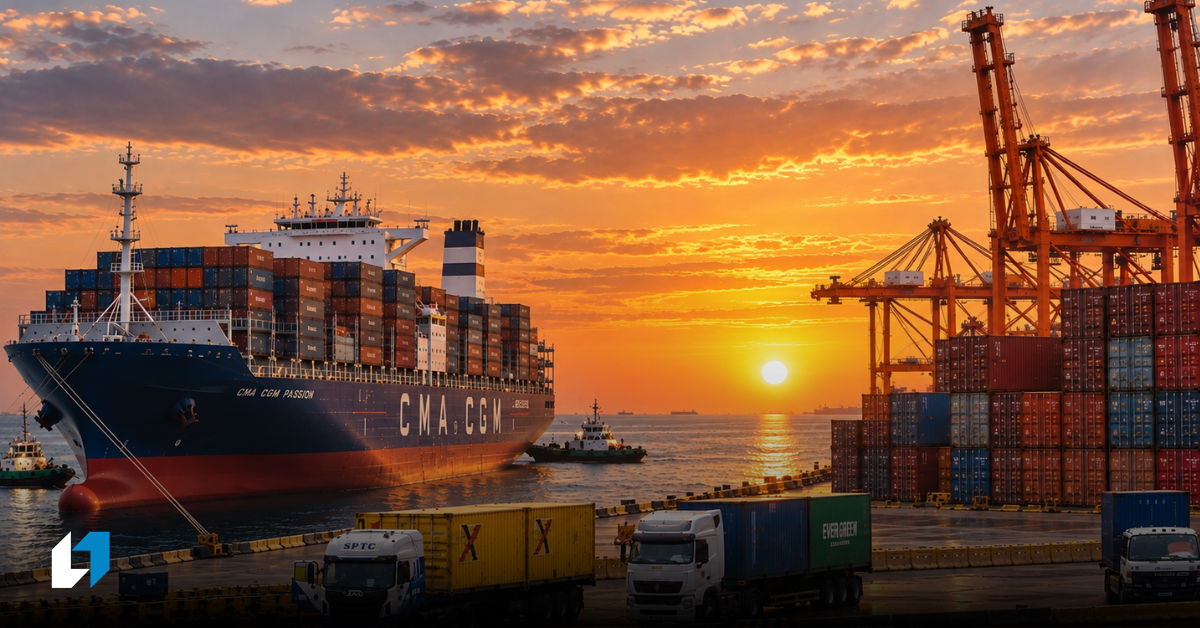
A military confrontation in the Middle East can raise the price of fuel in Manila. A disruption in East Asia can affect factories in Philippine economic zones. A technology dispute between major powers can affect semiconductor demand and investment. And when these shocks push up inflation and weaken the peso, the effects can eventually reach interest rates, corporate profits and stock valuations.
Prof. Janek Ratnatunga, CEO of the Institute of Certified Management Accountants of Australia and New Zealand, recently offered a provocative way of looking at these risks.
In his article, “World War III Ignites: The Multiple Battles Shaping the Conflict,” Ratnatunga argues that a third world war should not necessarily be imagined as another 1939, with clearly defined alliances fighting across conventional battlefields. Instead, he sees today’s conflicts as taking place simultaneously across military, economic, technological, financial and environmental fronts.
Whether these overlapping conflicts should actually be called “World War III” is debatable. But his framework raises a useful question for the Philippines: What happens when several global risks hit a highly interconnected economy at the same time?
The first front is energy
The Philippines has already seen how quickly a distant conflict can become a domestic economic problem.
In June, the Bangko Sentral ng Pilipinas said the inflation outlook had “significantly shifted upward” because of conflict in the Middle East. It cited higher global oil and non-oil prices, peso depreciation and higher fuel and fertilizer costs. The Monetary Board raised its policy rate by 25 basis points to 4.75 percent on June 18.
The transmission from conflict to Filipino households can therefore be surprisingly direct.
Higher oil prices increase fuel and transportation costs. Higher transportation costs can make food and other goods more expensive to move. Fertilizer costs can affect agricultural production. Businesses that use energy and imported inputs face pressure on margins.
If higher import costs also weaken the peso, the effect can become self-reinforcing because a weaker currency makes dollar-priced commodities more expensive in peso terms.
In June alone, the Philippines imported $1.62 billion of mineral fuels, lubricants and related materials.
For the Philippines, an oil shock is therefore not merely an energy story. It can become an inflation, currency, interest-rate and consumption story.
The second front is trade
The same vulnerability appears in trade.
In July 2026, Philippine imports reached $14.12 billion compared with exports of $8.15 billion. That left the country with a merchandise trade deficit of $5.97 billion.
More revealing is where those goods come from. China accounted for 29.5 percent of Philippine imports in July. South Korea supplied another 12.7 percent and Japan 7.9 percent. Overall, East Asia supplied 54.5 percent of Philippine imports.
This means a serious disruption in East Asian trade routes or production networks could affect Philippine companies even if the Philippines itself were not directly involved in a conflict.
And the exposure works in both directions.
East Asia accounted for 45.3 percent of Philippine exports in July. Hong Kong alone received 15.9 percent, China 11.3 percent and Japan 10.5 percent.
The Philippine economy therefore depends considerably on the same region both as a source of goods and as a destination for exports.
The third front is technology
This becomes even more important when electronics are considered.
Electronic products accounted for 58.8 percent of Philippine exports in July, generating $4.79 billion. Electronics were also the country’s largest import category at $4.60 billion.
This illustrates something important about modern manufacturing.
The Philippines does not simply manufacture a product from beginning to end and ship it overseas. It participates in international production networks in which components can cross borders several times before the final product reaches a consumer.
This makes semiconductors and electronics more than an export story. As advanced chips, artificial intelligence, computing power and technology increasingly become part of the strategic competition among major economies, the global electronics supply chain can also become a geopolitical issue.
For the Philippines, this creates both risk and opportunity.
Companies may seek to diversify production away from locations they consider geopolitically vulnerable. The Philippines could potentially capture some of that investment. But its existing dependence on interconnected Asian electronics supply chains also means severe disruption could affect production and exports.
The same industry can therefore represent an opportunity for diversification and a source of vulnerability.
The fourth front reaches financial markets
Global conflict does not have to reach Philippine territory to reach Philippine investors.
A conflict that sends oil prices higher can eventually affect Philippine asset prices. More expensive oil can push inflation higher and put pressure on the peso. Persistent inflation can keep interest rates elevated, while greater uncertainty can lead investors to demand higher returns. As the required return on investments rises, the valuations investors are willing to pay for stocks can decline.
This is why geopolitical risk can eventually appear in the price of Philippine stocks and bonds.
If investors demand a higher return for holding Philippine assets, the discount rate applied to future corporate earnings rises. Even if expected profits do not immediately change, higher required returns can reduce the price investors are willing to pay for those earnings.
Companies can also face higher financing costs.
Consumers may cut discretionary spending if food, transportation and electricity consume more of household budgets. Businesses dependent on imported materials may see margins compressed.
What begins as a geopolitical event can therefore end up affecting earnings, valuations and investment decisions.
The bigger risk is several shocks arriving together. This is where Ratnatunga’s framework becomes particularly useful for thinking about the Philippines.
Economies are accustomed to dealing with individual shocks.
An oil shock can be addressed through monetary and fiscal policy. Businesses can adjust to a weaker peso. Manufacturers can look for alternative suppliers. Companies can manage higher interest rates.
But the problem becomes more complicated when the shocks are connected.
Consider a situation in which oil prices rise at the same time that the peso weakens. Food prices then increase while shipping becomes more expensive. Supply chains are disrupted while export demand slows. Inflation remains elevated, limiting the BSP’s ability to lower interest rates.
Each problem makes another problem harder to solve. There is already evidence of how important imported inputs are to the Philippine economy. In July, raw materials and intermediate goods accounted for 40.4 percent of total imports, while capital goods represented another 27.2 percent.
This means disruptions abroad can affect not only what Filipinos consume but also what Philippine companies need in order to produce.
Resilience becomes an economic advantage
Ratnatunga’s article is deliberately provocative. His argument is that the world may already be experiencing something resembling a global conflict, except that the battlefields now extend beyond conventional warfare.
For the Philippines, it may be less important to decide what to call this period than to understand what it exposes.
Energy dependence matters. Trade concentration matters. The structure of Philippine exports matters. Domestic food production matters. The ability to attract investment into higher-value industries matters.
So does the country’s ability to withstand several external shocks simultaneously.
The latest trade numbers illustrate the extent of that interconnectedness. From January to July 2026, Philippine exports reached $54.92 billion, while imports reached $92.26 billion. Both were the highest January-to-July values since the statistical series began in 1991.
Global integration has brought the Philippines enormous opportunities. But integration also means that economic distance is no longer measured simply in kilometers.
A war can be thousands of kilometers away and still reach the Philippines through an oil tanker, a semiconductor shipment, an exchange rate or an interest-rate decision.
This may ultimately be the most useful lesson from Ratnatunga’s argument. The Philippines does not have to be on the battlefield to feel the economic consequences of a world increasingly divided across many fronts.