People often imagine that financial success comes from one major breakthrough—a promotion, a profitable investment, a successful business, or an unexpected windfall. These moments can help, but they rarely explain why some people steadily improve their lives while others remain financially stuck despite earning more over time.
The more powerful difference is often found in ordinary decisions that attract little attention: how much a person saves from each paycheck, whether debt is paid down or allowed to grow, and whether good financial habits continue even when progress feels slow. Each choice may appear insignificant on its own, but repeated over many years, it can shape a person’s financial future.
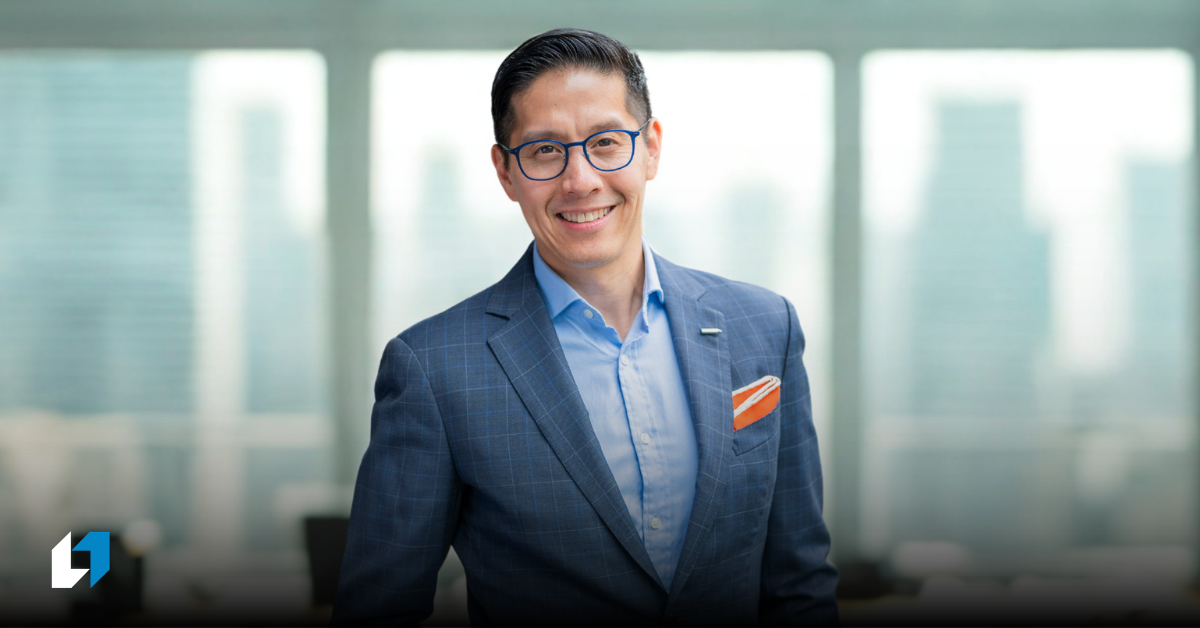
As Registered Financial Planner Edric Mendoza approached 50, he began noticing how the decisions people made over many years had shaped where they eventually ended up.
Some had built strong careers, stable finances, and healthy relationships. Others continued to struggle despite having similar opportunities. The difference, he observed, was rarely one dramatic decision. It was often the accumulation of small choices repeated over time.
“Consistency compounds,” Mendoza says.
The principle comes from leadership expert John Maxwell, whose teachings have influenced how Mendoza approaches leadership, work, family, and personal finance.
“Pretty straightforward line. But as an RFP, we get it. Small choices don’t seem to show much results at the start, But through time, these choices will compound exponentially into something good or bad,” he says.
Compounding is commonly associated with investments. Money earns a return, those earnings are reinvested, and the investment can grow faster over time.
But Mendoza believes the same principle applies beyond investment returns. Spending habits, savings discipline, debt payments, career decisions, and even relationships can all compound.
A person who saves a small amount every payday may not see an immediate change in financial position. After several years, however, those contributions and their investment returns can become substantial.
The opposite is also true. A small credit card balance may not appear dangerous at first. But when a borrower continues spending, carries the balance forward, and pays interest every month, a manageable obligation can eventually become a financial burden.
This is why Mendoza believes daily behavior can matter more than occasional bursts of effort.
People often wait for a higher salary, a large bonus, or a profitable investment before they begin improving their finances. Yet relying on a future breakthrough can distract them from the choices they can already make with the money they have today.
A person may not be able to invest a large amount immediately, but can begin investing regularly. Someone may not be able to repay all debts at once, but can consistently pay more than the minimum amount due. A household may not be able to eliminate every unnecessary expense, but can begin controlling one or two recurring costs.
The first results may appear insignificant. The value comes from repeating the action long enough for it to accumulate.
Mendoza says the truth of this principle became clearer as he reached midlife and observed the lives of people around him.
“I see this now especially that I am hitting 50 and the ‘midlife’ mark. I see friends, relatives, colleagues, contacts far and wide, and even just people at a distance. It is 100% true. I see it in my own life! So I’ve made it a point to continue to be as intentional as possible in the daily decisions and disciplines I have and make. Each of these choices will compound. I like to say that life is the sum of the choices we make.”
His observation highlights why financial knowledge alone does not guarantee financial success.
Many people already know that they should save, manage debt, invest for retirement, and avoid spending beyond their income. The harder part is applying that knowledge consistently, especially when the benefits are not immediately visible.
An employee may understand the importance of retirement planning but postpone investing until the next salary increase. A young professional may know the value of an emergency fund but continue spending any surplus. An investor may have a sound long-term strategy but abandon it when the market falls.
In each case, the problem is not necessarily a lack of information. It is the failure to turn knowledge into a repeated discipline.
Consistency can also be difficult because financial progress is rarely smooth. Unexpected medical expenses, job losses, business setbacks, family responsibilities, and market declines can interrupt even a well-designed plan.
Mendoza draws strength from another Maxwell principle: “Everything worthwhile is uphill.”
“Great reminder constantly that grit and hardwork should be our breakfast. It is sobering and even a bit daunting. But so true. It is a necessary mindset so that even as we start something we brace ourselves for challenges and are able to weather them better, rather than being naive and too idealistic that we get discouraged and quite when the going gets tough. This too has helped me weather many challenges.”
The lesson applies directly to building wealth.
People may begin saving with enthusiasm, only to lose motivation when progress appears slow. Investors may become impatient when their portfolios fail to produce immediate returns. Business owners may abandon sound plans when the first few years prove more difficult than expected.
Expecting the journey to be challenging can help people respond differently. Instead of treating every setback as evidence that the plan has failed, they can make adjustments and continue.
Consistency does not mean refusing to change. A financial plan should evolve when income, family responsibilities, priorities, and economic conditions change. But the underlying discipline of saving, controlling debt, investing, and planning for the future should remain.
For Mendoza, being intentional about daily decisions is important because both good and bad choices can compound.
A small increase in lifestyle spending can become a permanent monthly expense. A decision to delay investing can turn into several lost years. A habit of borrowing for nonessential purchases can slowly consume future income.
Positive decisions also build on one another. Regular savings create an emergency fund. An emergency fund reduces the need to borrow during a crisis. Lower debt allows more money to be invested. Growing investments can eventually provide greater financial security and freedom.
No single step may appear transformative on its own. Taken together over many years, however, these decisions can lead to a completely different financial outcome.
For people who feel overwhelmed by the size of their financial goals, Mendoza’s lesson offers a more practical starting point. They do not need to transform everything immediately. They need to identify one sound decision they can repeat.
It may be saving before spending, making a fixed monthly investment, paying down high-interest debt, or reviewing expenses every payday.
The amount may initially seem small. The result may not be visible for months or even years. But that is the nature of compounding.
Financial success is not always created by one extraordinary opportunity. More often, it grows quietly through ordinary choices made consistently.
As Mendoza puts it, “Consistency compounds.”