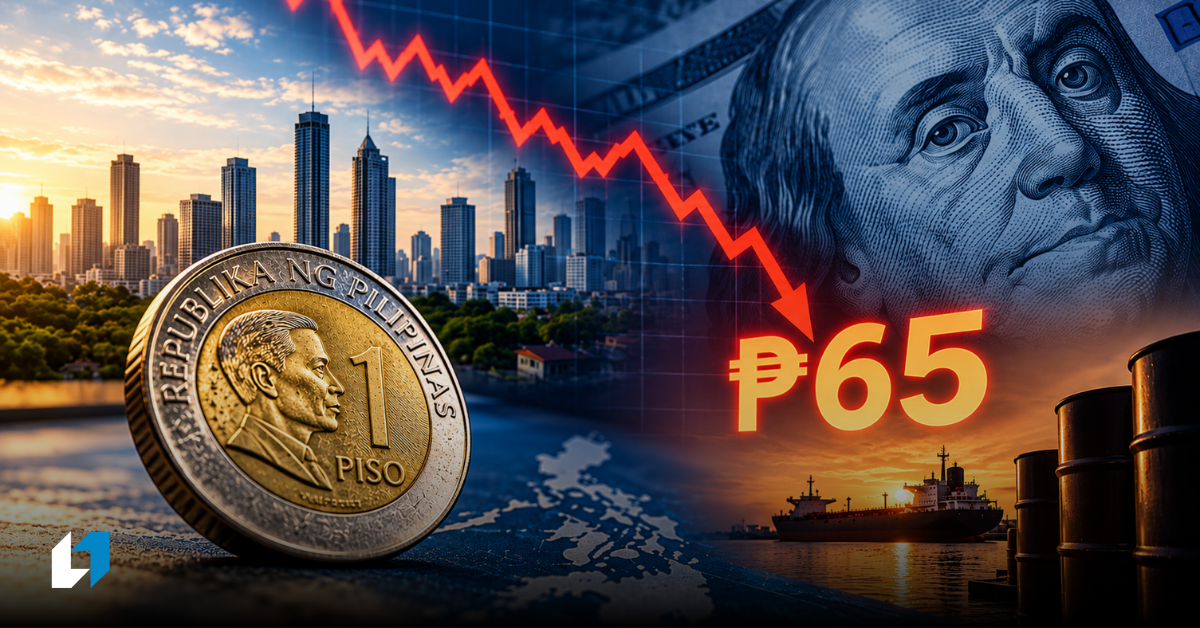
The Philippine peso is moving closer to ₱65 against the US dollar, a level that seemed unlikely just a few months ago. With the exchange rate reaching a new record low of ₱63.52 on October 22, the currency needs to depreciate by only another 2.3 percent to reach that level.
In May 2026, when the peso was trading at approximately ₱61.70, financial analyst Henry Ong warned in his Philippine Daily Inquirer column, “Why the peso could weaken to 65:$1,” that persistent external deficits, higher oil prices, and political uncertainty could push the currency toward ₱65.
Five months later, the peso has weakened considerably, and the economic pressures identified in that earlier analysis have intensified.
The Philippines’ balance of payments deficit has widened, global oil prices remain elevated, and the peso continues to face pressure despite higher interest rates from the Bangko Sentral ng Pilipinas (BSP).
These developments suggest that ₱65 is no longer a distant possibility. Unless the country’s external financing position improves, the peso could reach that level sooner than expected.
Why the country’s dollar deficit matters
One of the main reasons behind the peso’s continued depreciation is the persistent imbalance between the country’s foreign exchange inflows and outflows.
The Philippines imports considerably more goods than it exports. Although remittances from overseas Filipinos, business process outsourcing revenues, and other service receipts provide substantial dollar inflows, these have not been sufficient to offset the country’s external financing requirements.
The latest figures from the BSP illustrate how this imbalance has worsened.
During the first nine months of 2026, the Philippines recorded a balance of payments deficit of $9.1 billion, compared with a deficit of $5.3 billion during the same period last year. This represents an increase of approximately 72 percent.
The balance of payments measures the country’s overall transactions with the rest of the world, including trade, investments, and financial flows. A deficit indicates that foreign exchange outflows have exceeded inflows on an overall basis.
When this happens, the country must finance the difference through available foreign exchange resources and adjustments in its international financial position.
The BSP currently expects the balance of payments deficit to reach $9.2 billion for the whole of 2026.
This means that the deficit accumulated during the first nine months has already reached almost 99 percent of the projected full-year amount.
Although seasonal remittances and other inflows could improve the position during the final quarter, the figures suggest that external pressures remain substantial. More importantly, the problem is unlikely to disappear next year.
The BSP projects a balance of payments deficit of $8.5 billion in 2027, while the current account deficit is expected to remain elevated at $19.4 billion.
The current account measures the country’s trade in goods and services, income flows, and transfers. A persistent deficit indicates that the economy continues to require financing from abroad.
These projections suggest that the peso’s weakness reflects a structural problem rather than a temporary market disturbance.
Why oil prices could push the peso lower
The country’s dependence on imported petroleum is another major source of pressure on the exchange rate.
Because international oil transactions are generally denominated in US dollars, higher crude oil prices increase the amount of foreign currency that Philippine importers must purchase.
This creates additional demand for dollars and can contribute to further peso depreciation.
Recent geopolitical tensions in the Middle East have pushed Brent crude oil above $110 per barrel, raising concerns about the cost of petroleum imports.
For the Philippines, the effect is particularly significant because the country relies heavily on imported fuel to support transportation, electricity generation, and industrial activity.
Higher oil prices therefore affect the economy through two channels.
First, they increase the country’s import bill, which can widen the trade deficit and place additional pressure on the peso.
Second, they raise domestic production and transportation costs, which can contribute to higher inflation. This creates a difficult situation for policymakers.
A weaker peso makes imported oil more expensive in local currency terms. Higher fuel costs can then contribute to inflation, which may further weaken confidence in the peso.
The result is a cycle in which currency depreciation and higher import costs reinforce each other. Unless international oil prices decline substantially, this pressure could persist in the coming months.
Why higher interest rates have not stopped the decline
The BSP has attempted to contain inflationary pressures through higher interest rates.
On October 22, the central bank raised its benchmark policy rate by 50 basis points to 5.50 percent, a larger increase than financial markets had expected.
The decision represented the fourth consecutive interest rate increase since April.
Normally, higher domestic interest rates should provide some support for the peso because peso-denominated investments become more attractive relative to foreign assets.
However, the peso continued to weaken despite the latest adjustment.
After initially strengthening, the currency reversed its gains and closed at a new record low of ₱63.52 against the dollar.
This development suggests that higher interest rates alone may not be sufficient to offset the economic pressures affecting the exchange rate.
Investors consider more than the nominal interest rate offered by a country.
They also assess inflation expectations, economic growth, external financing requirements, and the possibility of further currency depreciation.
If investors expect the peso to weaken by more than the additional interest income they could earn from peso-denominated assets, higher interest rates may not be enough to attract foreign capital.
This helps explain why monetary tightening does not always produce an immediate currency recovery.
The BSP can influence domestic interest rates, but it cannot directly reduce global oil prices or eliminate the country’s trade deficit.
The peso therefore remains vulnerable to external developments even as monetary policy becomes more restrictive.
Is the peso’s uncertainty premium increasing?
In his May Inquirer column, Ong introduced a framework that explained the exchange rate as a combination of the peso’s underlying economic value and an additional premium associated with uncertainty.
He suggested that the peso’s structural fair value could be approximately ₱58 after adjustments for external deficits and the country’s dependence on imported oil.
At the exchange rate of ₱61.70 prevailing at the time, the difference of ₱3.70 could partly represent an uncertainty premium demanded by investors.
Using the same illustrative benchmark today produces a considerably wider gap.
At ₱63.52, the difference between the market exchange rate and the assumed structural fair value of ₱58 has increased to ₱5.52.
This represents an increase of approximately 49 percent in the residual exchange rate gap since May.
However, the entire difference cannot automatically be attributed to political uncertainty.
Higher oil prices, changes in international interest rates, inflation expectations, and external financing conditions may also have altered the peso’s underlying economic value.
Nevertheless, the wider gap is consistent with an environment in which investors demand greater compensation for holding peso-denominated assets.
Political uncertainty can contribute to this adjustment by affecting confidence in economic policy, fiscal management, and the country’s investment environment.
When investors become more cautious, they may reduce their exposure to local financial assets and increase their holdings of foreign currency.
Such adjustments can place additional pressure on the peso even without a major financial crisis.
The important point is that currency depreciation does not necessarily require a sudden collapse in economic conditions.
It can occur gradually as markets reassess the risks associated with a country’s long-term economic outlook.
How close is ₱65?
The peso’s depreciation since May provides a useful perspective on how quickly the exchange rate can change.
When Ong published his earlier forecast, the peso was trading near ₱61.70.
At the October 22 closing rate of ₱63.52, the currency has weakened by ₱1.82 against the dollar in approximately five months. To reach ₱65, the peso needs to depreciate by another ₱1.48.
This means that the remaining distance to ₱65 is already smaller than the depreciation recorded since May.
In percentage terms, a move from ₱63.52 to ₱65 would require additional depreciation of approximately 2.3 percent.
If the peso were to weaken at a pace comparable to the past five months, the exchange rate could reach ₱65 within the next several months.
This is not a prediction that the currency will depreciate at a constant rate. Exchange rates are influenced by changing economic conditions and can experience substantial short-term fluctuations.
However, the calculation illustrates why ₱65 is now a plausible near-term scenario rather than a distant possibility.
The peso could still recover temporarily if seasonal remittances increase dollar supply, oil prices decline, or global financial conditions improve.
The BSP also maintains substantial international reserves that can help reduce excessive exchange rate volatility.
As of September, the country’s gross international reserves stood at approximately $99.5 billion, equivalent to about 6.2 months of imports and payments for services and primary income. These reserves provide an important buffer against external shocks.
However, foreign exchange reserves cannot permanently eliminate the economic imbalances that contribute to currency depreciation.
A sustained improvement would require stronger export earnings, more stable capital inflows, lower import costs, or some combination of these developments.
Why ₱65 is becoming more likely
The case for further peso depreciation has strengthened because several economic pressures are occurring at the same time.
The balance of payments deficit has widened considerably, oil prices remain elevated, and the BSP expects the current account deficit to persist through 2027.
At the same time, the peso has continued to weaken despite successive increases in domestic interest rates.
These developments suggest that the exchange rate is responding to more than temporary speculation or short-term market sentiment.
The peso’s weakness reflects the country’s continuing dependence on foreign currency financing and its vulnerability to global energy prices.
In May, when the peso was near ₱61.70, the possibility of reaching ₱65 required additional depreciation of approximately 5.3 percent.
Today, at ₱63.52, the required adjustment has narrowed to just 2.3 percent.
The difference is significant because the economic conditions that could drive that adjustment remain largely unresolved. Although seasonal inflows and BSP intervention could temporarily stabilize the currency, they may not be sufficient to reverse the broader depreciation trend unless the country’s external position improves.
The peso does not need another major economic shock to reach that level. A continuation of the depreciation already observed over the past several months would be enough.
Unless external deficits narrow, oil prices ease, or investor confidence improves considerably, the peso could reach ₱65 sooner than expected.