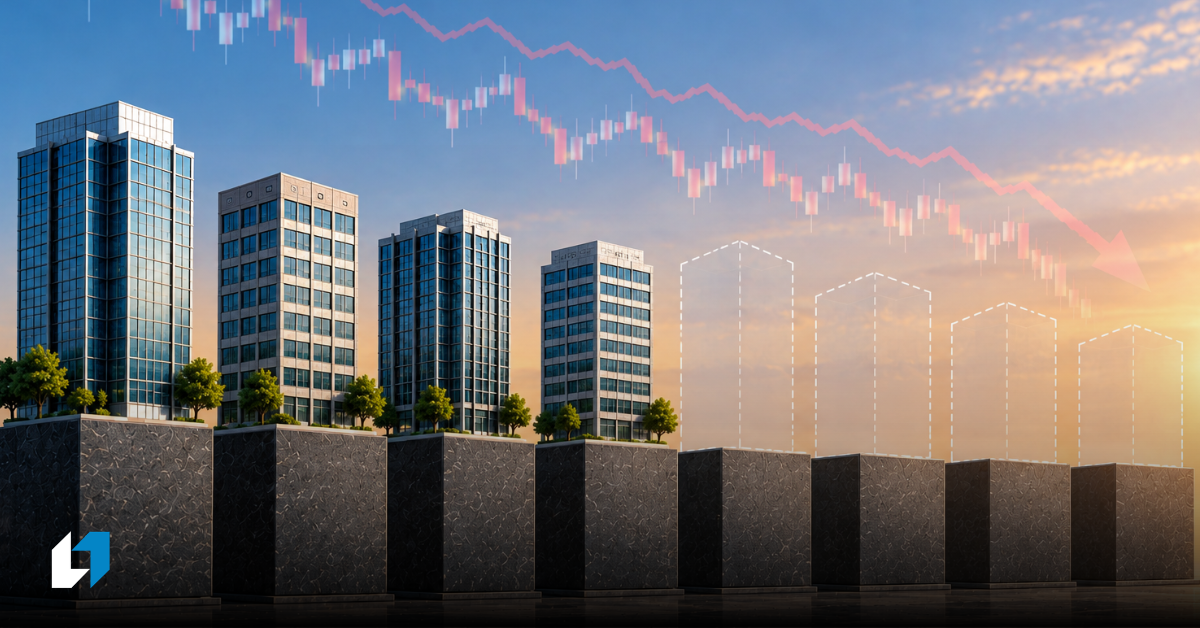
The bigger challenge for the Philippine stock market may not be companies leaving the exchange, but the lack of new companies coming in to replace them.
When a listed company decides to leave the Philippine Stock Exchange, investors understandably pay attention.
But Securities and Exchange Commission Chairman Francis Lim believes the more important problem lies elsewhere.
“The deeper problem is not simply that our companies are leaving the stock market,” Lim said. “It is that too few new companies are coming in.”
Lim made the remarks as guest speaker during the Financial Executives Institute of the Philippines’ 9th General Membership Meeting on Sept. 16 at Fairmont Makati.
His observation points to a different way of looking at the weakness of the Philippine stock market. Perhaps the market does not simply have a demand problem. It also has a supply problem.
Where are the new companies?
The Philippines does not lack businesses that could eventually tap the capital market.
Lim cited a corporate base that includes about 100,000 small corporations, 42,000 medium-sized companies and nearly 8,000 large corporations.
“Of course, not everyone is ready for the public market today,” he said. But as companies grow, so do their ambitions and their need for capital.
If the country has thousands of large corporations and tens of thousands of medium-sized ones, why do relatively few eventually find their way to the stock exchange?
Lim believes the capital market should become part of the growth path of these businesses.
“We should not make the capital market a destination companies reach only when they are already big,” he said. “We should make it a platform on which they become bigger.”
This changes the way an IPO should be viewed. A company does not need to wait until it has reached the limits of private ownership before going public. The stock market can provide capital for expansion, acquisitions and the next stage of growth.
But that works only if entrepreneurs believe the benefits of becoming public justify the costs.
The economics of being listed
Going public is not free. A listed company accepts greater disclosure, accountability and regulatory obligations. Management also becomes accountable to outside investors and must operate under greater public scrutiny.
Lim acknowledged those obligations directly, but he also argued that they should come with meaningful economic benefits.
“Those obligations must be matched by real benefits,” he said, citing access to capital, credible price discovery, liquidity and broad investor participation.
This is where the decision becomes economic rather than ceremonial.
For a business owner, the relevant comparison is not simply whether an IPO can raise money. The company must compare public ownership with other sources of capital.
It may borrow from banks. Existing owners may inject additional equity. A strategic investor can take a stake. Private equity may provide capital without requiring the company to become publicly traded.
The stock exchange therefore has to compete for companies just as companies compete for investors and when the benefits of being listed become too small, the calculation changes.
“If shares barely trade, public ownership is too thin, or the cost of being public consistently outweighs the benefits, we should listen to what those signals are telling us,” Lim said.
The family business problem
This may be particularly relevant in the Philippines, where many successful businesses remain closely held.
For an entrepreneur who has spent decades building a company, an IPO can appear to mean giving up part of the business, accepting outside investors and exposing decisions that were previously private.
Lim challenged that perception. “Going public doesn’t mean giving up your legacy,” he said. “It can be the way your legacy endures.”
“A family enterprise can become an institution, one that outlives its founders, creates opportunities for generations, and contributes to the country for decades to come.”
This is an important argument because the supply of listed companies ultimately depends on decisions made by business owners.
Regulators can simplify registration. Exchanges can reduce barriers. Investment banks can encourage IPOs, but someone still has to decide that public ownership is worthwhile.
Rethinking an old IPO rule
Lim’s interview after his speech also revealed that some of the mechanics of bringing companies to market are being reconsidered.
One issue involves the allocation of shares during an IPO.
Lim said that under the existing arrangement, 20 percent of an offering is automatically allocated through brokers on a pro rata basis. He noted that the system has attracted questions, including concerns from foreign investors.
“So we are reviewing that,” Lim said. He went further: “My own preference is to remove it.”
He stressed, however, that the SEC was still studying the options and their impact. If the Philippines wants more companies to enter the public market, it has to examine the entire process from the perspective of a potential issuer.
Every additional cost, restriction or structural disadvantage affects the calculation of whether going public is worth it.
This does not mean investor protection should be weakened. An easier IPO process that produces poor disclosure or weaker governance would create a different problem.
The challenge is to remove obstacles that do not provide enough corresponding benefit.
A pipeline, not an occasional IPO
Lim’s argument suggests that success should not be measured by celebrating one large IPO every few years.
A functioning capital market needs a pipeline. Some small companies should grow into medium-sized businesses. Some medium-sized businesses should become large corporations. And some of those companies should eventually use the public market to finance their next stage of growth.
This process continually introduces new businesses, industries and investment opportunities into the stock exchange.
“The market cannot grow if it is not renewed,” Lim said.
“We need a stronger pipeline of companies entering the market, and a stronger market that gives them reasons to stay.”
For investors, more listings would mean more than having additional ticker symbols on a trading screen. A bigger market could give investors exposure to businesses and industries that remain largely outside the exchange today. It could also reduce the dependence of the Philippine market on a relatively small group of large, established companies.
For companies, meanwhile, a deeper public market could provide another source of long-term capital beyond banks and private investors.
The Philippine stock market therefore faces two separate challenges. It has to convince investors that listed companies are worth owning, but before that can happen on a larger scale, it also has to convince more Philippine companies that being listed is worth it.