The Philippines once helped Vietnam learn about capital markets. Two decades later, Vietnam has moved ahead, while the Philippine market struggles to keep pace with its ASEAN neighbors.
In 2005, representatives from Vietnam came to the Philippines to learn from our experience in developing a stock market.
More than two decades later, the student appears to have overtaken the teacher.
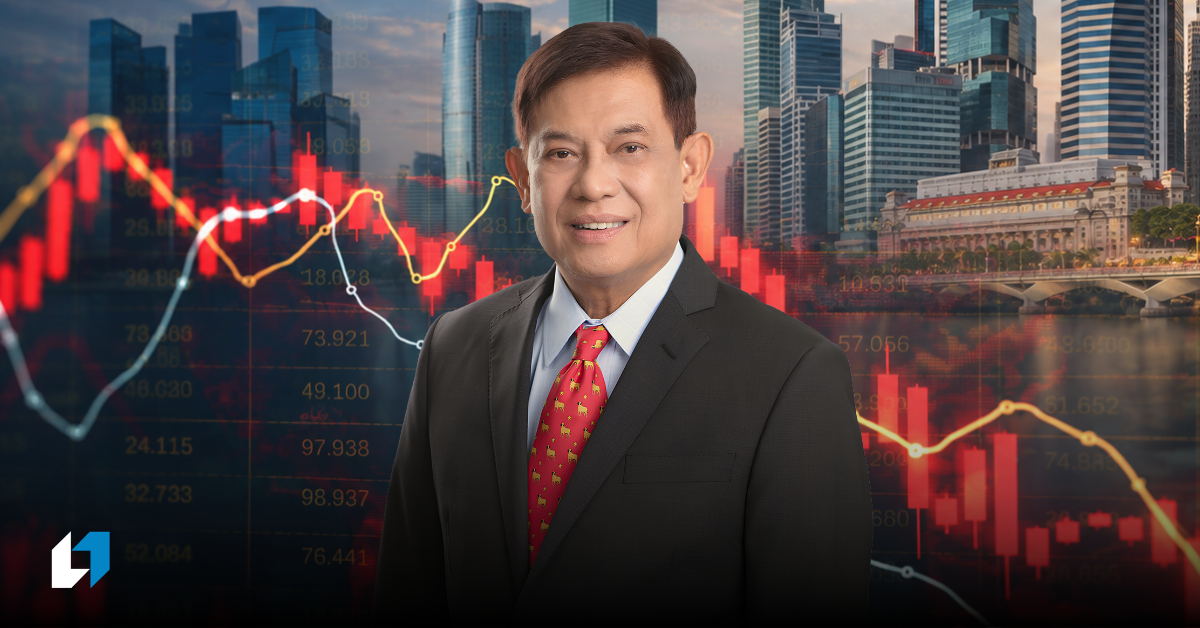
“When I was President of the Stock Exchange in 2005, Vietnam came here because they wanted to share our experience,” Securities and Exchange Commission Chairman Francis Lim recalled. “We taught them and now the Ho Chi Minh Stock Exchange has moved ahead of us.”
Lim made the remarks as guest speaker during the Financial Executives Institute of the Philippines’ 9th General Membership Meeting on Sept. 16 at Fairmont Makati.
His comparison with Vietnam offers a useful way to understand what has happened to the Philippine stock market. While much attention is usually placed on where the PSEi is headed next, a longer-term problem has emerged. The Philippine capital market has steadily lost ground against several of its ASEAN neighbors.
Falling behind
Lim presented numbers that illustrate the gap. As of Aug. 31, 2026, the Philippines had only 279 listed companies. Vietnam had 405, Singapore 604, Thailand 867 and Indonesia 962.
This leaves the Philippines with the second-smallest listed-company base in ASEAN, ahead only of Cambodia, according to Lim.
The comparison is striking because the Philippines is hardly a newcomer to capital markets. Lim noted that the local stock market traces its history to 1927.
Age, however, has not translated into regional leadership.
“We have lost ground,” Lim said. “Now we must recover it and then move again.”
The experience of Vietnam is particularly revealing because its capital market developed much later. Yet the country has managed to build a broader listed-company base and push ahead with reforms that helped its market expand.
What did the others do differently?
During an interview after his speech, Lim was asked what other Asian markets had done differently.
His answer suggests that there was no single reform that transformed these markets. Rather, neighboring countries made a series of changes over time.
Lim said some markets actively went out and invited companies to list. They liberalized rules and introduced mechanisms such as market making and margin financing. At the same time, they strengthened corporate governance and enforcement against abuses such as market manipulation and insider trading.
Individually, these measures may appear incremental. Collectively, they can change how a capital market functions.
Lim summed up part of the Philippine experience rather simply.
“There were little things that we were supposed to do that we didn’t do,” he said.
Capital markets develop through an ecosystem. Companies need reasons to raise money through the market. Investors need enough choices and sufficient confidence to commit capital. Intermediaries need incentives to participate, while regulators need rules that protect investors without making the market unnecessarily difficult to access.
When neighboring countries improve these elements faster, their markets can compound those advantages over many years.
Trust also matters
Lim also emphasized an element that is sometimes treated separately from market development: enforcement.
He argued that actions against market abuse and investment fraud should not be viewed simply as regulatory policing.
“These actions are separate from capital market development,” Lim said, before answering his own point: “They are not. They are capital market development.”
His explanation was straightforward: “Because capital follows trust.”
Investors are more willing to commit money when they believe disclosures are reliable, market prices are credible and those who manipulate the market will be held accountable.
“Trust is not an accessory to the capital market,” Lim said. “Trust is its foundation.”
This has economic consequences. Investors price uncertainty. The less confidence they have in information, governance and market integrity, the greater the return they may demand before putting money at risk. A higher required return, in turn, can translate into lower valuations and a higher cost of equity for companies.
This means enforcement and capital formation are not necessarily competing objectives. A market that is easier to access but harder to trust may attract neither long-term investors nor high-quality companies.
The economy matters too
Lim acknowledged that capital-market reforms alone cannot determine stock-market performance.
“The health of the general economy is a very big factor,” he said during the interview. “The health of the general economy is the better it is for the stock market.”
This is particularly relevant when comparing ASEAN markets.
Economic growth, corporate earnings, foreign investment, interest rates, currency movements and political conditions can all influence how investors allocate capital across countries.
A strong economy does not automatically produce a strong stock market, but it provides a more favorable environment for businesses to grow and investors to take risk.
The opposite can also happen. When economic or political uncertainty rises, investors may demand a larger risk premium. Even profitable companies can then trade at lower valuation multiples.
That is why the challenge facing the Philippines extends beyond getting the PSEi back to a particular level.
A race that does not stop
Perhaps the most important lesson from Lim’s Vietnam story is that capital-market leadership is not permanent.
The Philippines had experience that Vietnam once wanted to learn from. Vietnam then adopted its own reforms and continued to develop its market.
Twenty-one years later, Lim is now pointing to Vietnam as an example of a market that has moved ahead.
The comparison should not necessarily be interpreted as proof that everything Vietnam did should be copied. Markets differ in their economies, institutions and investor bases. But it demonstrates what can happen when one market changes faster than another over a long period.
The Philippine market still has advantages. It has established institutions, experienced financial professionals and a large domestic corporate sector.
But history alone does not create a competitive capital market. As Lim told his audience, “We have lost ground.”
The challenge now is not simply to recover what was lost. It is to understand how the Philippines, once a market that others came to study, can compete again in an ASEAN capital market that did not wait for it to catch up.