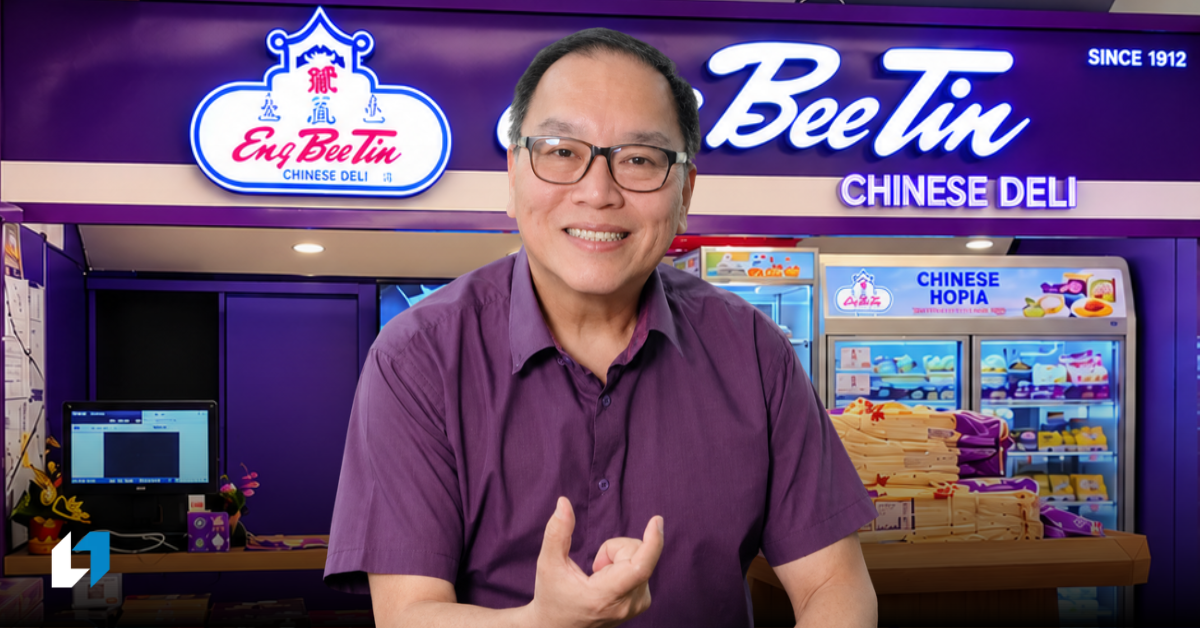
Before Gerry Chua became known as Mr. Ube, the entrepreneur behind the popular Eng Bee Tin hopia brand, he was a college student who spent much of his time worrying about how to keep his family’s struggling bakery from running out of money.
While other students were concerned about their studies and future careers, Chua was preoccupied with unpaid obligations, insufficient bank balances, and checks that could bounce at any moment.
The financial problems had become so serious that the family sometimes faced as many as eight bounced checks in a single day.
“Hanggang isang araw, nung nag-aaral na ako sa PSBA, halos araw-araw nagba-bounce tseke namin. Every day, eight checks a day. Yung Chinabank araw-araw tumatawag sa nanay ko,” Chua recalled in an interview with Financial Adviser PH.
The difficulties were made worse by the absence of proper financial records. His father had accumulated obligations, but the family did not have a clear accounting of how much was owed or when payments were due.
“Wala na yong lolo ko nun eh. Ang masama walang record yung tatay ko. Di alam kung magkano yung inutang at babayaran. Araw-araw inaantay, inaantay ko na lang yung tawag ng bangko. Magkano kulang?”
For a small business, this situation can be particularly dangerous. When owners do not maintain accurate records of their debts and payment schedules, they lose the ability to anticipate cash shortages and make informed financial decisions.
A business may continue operating despite weak sales, but without reliable information about its obligations, even routine payments can become a daily crisis.
The problem was not simply that Eng Bee Tin lacked sufficient money. The family also lacked the financial visibility needed to determine how much cash it would require to meet its commitments.
For entrepreneurs, maintaining proper financial records is therefore more than an administrative responsibility. It is an essential part of protecting the business from avoidable financial distress.
At the time, Eng Bee Tin was still relatively unknown, and customer demand for its hopia remained weak.
Chua recalled that selling just 50 pieces of hopia was already a reason for celebration.
“Yung time na yun, sa totoo lang, ito nakakahiya mang sabihin. Nasa eskwelahan ako, wala akong iniisip kung di magkano utang namin. Magkano babayaran? Magkano hahabulin ko?”
“Kasi ang masama noong time na yun, walang bumibili ng hopia talaga. Wala, kasi hindi nga kilala eh. Dati pag makabenta kami 50 na hopia, masayang-masaya na ako.”
The experience illustrates how weak customer demand can quickly develop into a financial problem, particularly when a business has obligations that must be paid regardless of its sales performance.
Even if a company has a product to sell, it cannot survive indefinitely when the cash it generates is insufficient to cover its operating expenses and debt payments.
For small businesses, the distinction between sales and cash flow is particularly important. Sales may indicate that customers are purchasing products, but the business must still collect enough money at the right time to pay its obligations.
In Eng Bee Tin’s case, the pressure of meeting those obligations became part of Chua’s daily life.
Instead of concentrating entirely on his education, he had to worry about how much money the family needed to deposit to prevent another check from bouncing.
The financial difficulties eventually led to an experience that Chua would remember years later.
One day, a manager at China Bank offered him additional time to cover a check that would otherwise be returned for insufficient funds.
“One time manager ng China Bank sabi niya ‘Gerry, ganito na lang, alam mo ba naghahabol ka naman eh. Bigyan kita hanggang 2 o’clock kasi pag 12:01 na, wala kang pondo, bounce na yung tseke eh’.”
The manager’s decision gave Chua a few additional hours to find the money.
“Sabi ko, ‘Thank you, thank you ha.’ Hindi ko kilala, pero alam niya kasi about me, alam mo naman yung balita sa Chinatown, wildfire yan eh.”
For an entrepreneur experiencing a liquidity crisis, even a short extension can make a difference.
A business that cannot meet an obligation at noon may still be able to pay later in the afternoon if it receives customer payments or obtains temporary financing.
However, relying on last-minute arrangements also exposes a business to considerable uncertainty. Its ability to meet financial obligations becomes dependent on circumstances that may be beyond the owner’s control.
Chua eventually managed to obtain the money he needed.
He arrived at China Bank at around 1:30 p.m., carrying ₱1,800 to cover the shortage.
But the manager who had offered him the extension was out for lunch.
“So 1:30 punta ako sa China Bank. Out for lunch yung manager pero nandun yung assistant. Hindi ko makalimutan ito, P1,800 pesos dala-dala ko. Alam magkano kulang ko, P1,800.”
Chua asked the assistant to authorize the transaction so that he could deposit the money before the extended deadline.
However, the assistant refused.
“Sabi ko, baka pwedeng pirmahan mo lang kasi wala pa yung manager para madeposit ko na, pero ayaw initialan para matanggap eh. Kaya iyak ako non.”
For Chua, the incident was particularly painful because he had already gone through the difficulty of finding the money.
The amount may appear small compared with the financial resources of established businesses today, but for a struggling bakery at that time, ₱1,800 represented the difference between covering a check and having it returned.
More importantly, the incident revealed how financially vulnerable the business had become.
Chua had no substantial cash reserve that could absorb an unexpected shortage. Every payment required another effort to find money, and even a minor delay could result in another bounced check.
This is why working capital management is critical for small businesses.
Entrepreneurs often concentrate on increasing sales and improving profitability, but they must also maintain enough liquidity to meet obligations as they fall due.
A business can report accounting profits and still experience financial distress if its cash collections do not match the timing of its payments.
In Chua’s case, the immediate problem was even more fundamental. Weak sales and existing obligations left little room for unexpected difficulties.
Despite his efforts, he had to accept that the check would probably bounce.
“Sabi ko na lang sa loob-loob ko, okay lang. Hindi naman araw-araw ganito ako eh. Eh di wala na, kinabukasan bounce. I expect mag-bounce talaga. Ganon lang, that’s life.”
He then recalled the emotional toll of the experience.
“Iyak ako, kasi hirap na hirap ako na maghabol ng pera. Nanghiram pa ako ng pera para madeposit tapos ayaw tanggapin.”
The incident shows a side of entrepreneurship that is rarely visible when people look at successful businesses.
Behind an established brand may be years of financial pressure, personal sacrifices, and difficult decisions that its owners had to confront before the company became commercially successful.
For Chua, the struggle was especially difficult because he was still a student. He had to deal with financial responsibilities that many entrepreneurs encounter only after years of business experience.
His experience also raises an important question for entrepreneurs: how long should they continue supporting a business that repeatedly struggles to meet its financial obligations?
Perseverance can be valuable, but it must be accompanied by efforts to address the underlying causes of financial distress.
Borrowing money to cover immediate obligations may prevent a temporary default, but it does not solve a business’s financial problems if sales remain insufficient and expenses continue to exceed available cash.
Without improvements in revenue, cost management, or financial planning, repeated borrowing can simply postpone the crisis while increasing the company’s obligations.
For small business owners, the lesson is to recognize financial warning signs before they become emergencies.
Repeated bounced checks, missing financial records, and constant efforts to borrow money for routine payments are indications that a business needs more than temporary financial assistance.
It needs a clearer understanding of its cash flow, a realistic assessment of its obligations, and a plan to restore financial stability.
Chua’s experience at China Bank did not provide an immediate solution to Eng Bee Tin’s problems. It was one episode in a much longer struggle to keep the family business operating.
Yet it also shows the determination that would later become part of his entrepreneurial journey.
When he found himself unable to deposit the ₱1,800 he had borrowed, Chua could do little more than accept the disappointment and prepare to face another day.
His experience offers an important reminder that entrepreneurship is not always about identifying opportunities and pursuing growth.
Sometimes, the immediate challenge is simply finding enough money to keep the business alive until the next day.